What is an ETF in Australia?
An exchange-traded fund, or ETF, pools investors’ money into an investment portfolio and has units that trade on an exchange. You buy units in the fund, rather than buying each underlying investment yourself. The fund’s strategy determines the exposure you receive.
The practical benefit is access: one order can give you a stake in a portfolio that would be awkward to assemble security by security. But “ETF” describes a way of investing, not a promise of safety, broad diversification or a particular return. Two funds with similar names can expose your money to quite different risks. MoneySmart’s ETF overview ↗.
Illustrative alternatives, not one fund’s portfolio. Your broker handles access and execution; it is not the ETF’s underlying portfolio.
You should be able to answer all three without relying on a recent performance chart.
This guide concerns Australian retail investors learning about exchange-traded funds. It explains the mechanics and a reading process, rather than choosing a fund or allocation for you. All numerical trade and cost examples below are invented unless explicitly identified as a dated official document example.
The ETF and your broker do different jobs.
The ETF issuer’s documents describe the investment objective and how the fund operates. Your broker or platform provides the route through which you place an order and maintain your account. A share registry may handle the fund’s holder records, contact details or distribution elections. These roles can sit behind different websites.
For example, buying a fund through Broker A does not turn it into Broker A’s investment strategy. If you later use Broker B, the fund’s disclosed objective has not changed merely because the account screen is different. Conversely, choosing a familiar platform tells you very little about the assets inside an unfamiliar ETF.
Keep two separate checks in your notes: “What is this fund?” and “How does this account hold and report my units?” Our CHESS holdings guide explains how to distinguish a personal HIN, an issuer-sponsored record and a provider’s custody arrangement. Do not infer the registration structure from an app balance alone.
What exposure am I buying?
Read the objective, strategy, assets and risks in the fund documents.
How will my units be recorded?
Read the platform’s holding terms and identify the records you should receive.
Betashares’ investor FAQ gives a concrete illustration of the registry role: its registrar handles certain holder-detail changes, statements and reinvestment enquiries. That is an example of administrative responsibilities, not an instruction to use the same registrar for every ETF. Follow the issuer’s own current contact route. Issuer FAQ and registry responsibilities ↗.
“ETF” does not tell you what is inside.
A fund might offer broad Australian shares, overseas shares, a single sector, bonds or another exposure. A passive strategy aims to follow an index or asset; an active strategy gives the manager investment choices within a stated objective. Also distinguish a fund that holds assets from one using derivatives to obtain exposure. MoneySmart identifies these differences and the additional considerations around complex strategies. ETF types and structures ↗.
Read the full fund name, exchange code and objective together. A short code is a useful identifier once you know the product. It is a poor substitute for the strategy. Words such as “global”, “income”, “technology” or “Australian” are starting points for investigation, not complete descriptions of what the manager can buy.
Try writing a one-sentence explanation with no promotional adjectives: “This fund aims to follow [benchmark] through [approach], giving exposure mainly to [assets and markets].” If you cannot fill the gaps from official documents, pause the comparison. You are still identifying the product, not choosing between similar alternatives.
Do the same with exclusions. Does “global” include Australia? Does a sector fund exclude businesses you expected to see? Are you comparing a broad portfolio with a narrow theme because both have “ETF” in their names? A useful comparison starts when the job of each fund is clear, rather than when their latest returns happen to fit on one chart.
Price, asset value and spread are different numbers.
An ETF’s net asset value, or NAV, measures its assets less liabilities, often expressed per unit. Its exchange price is the price at which units can trade. An indicative NAV, where available, estimates underlying value during the day. ASX explains these reference points alongside the role of market makers, which supply quotes that help trading take place. They do not make every price identical to NAV. ASX trading and NAV guidance ↗.
Spread: A$0.10 per unit · midpoint: A$50.00 · spread ÷ midpoint: 0.20%
In this fictional quote, buying 100 units at A$50.05 costs A$5,005 before brokerage. Immediately selling those same units at the unchanged A$49.95 bid would produce A$4,995 before brokerage: an A$10 difference. That is the full spread across a buy and an immediate sell, not an extra A$10 invoice charged on each side.
Relative to the A$50 midpoint, each side is A$0.05 away, or A$5 on 100 units. A live market can change while you act, and the displayed quantity matters. Use the example to understand the arithmetic, not to assume the displayed price will remain available for any order size.
ASX’s market-maker material explains that quotes are informed by the underlying portfolio and that spreads vary. A trading screen’s recent turnover is therefore only part of the picture. Check the actual bid, ask, quantities and relevant underlying market conditions rather than declaring an ETF easy to trade from one headline volume number. ASX market-maker arrangements ↗.
The fund fee is not the whole bill.
Separate costs incurred inside the fund from costs attached to your own account and orders. Betashares explains that fund fees generally accrue within the fund and are deducted from its assets periodically. They are not normally a separate annual debit you pay directly to the issuer. Read the actual fee disclosure, because a management-fee headline does not necessarily represent every cost. How ETF fees are collected ↗.
Holding the fund
Management fees, other disclosed costs and any applicable performance fee.
Making the trade
Brokerage and the prices available on the buy and sell sides.
Using the account
Any platform, service or other applicable account charges.
Here is a simple comparison. Assume a constant average investment of A$10,000 for a year and an annual fund cost assumption of 0.20%. The holding-cost approximation is A$20. If you also make two orders at A$5 brokerage each, that adds A$10. These two components total A$30, before spreads, taxes and other excluded costs.
Separate the holding cost from the trading cost.
One-year approximation with a constant average holding value and an assumed annual fund cost rate. Excludes spreads, taxes, platform fees and any additional fund costs. Fund costs are generally reflected in the fund’s assets, not a separate invoice from this calculator.
Notice how contribution size changes the effect of flat brokerage. Under an invented A$5-per-order tariff, an A$250 purchase has brokerage equal to 2% of that order value. An A$2,000 purchase has brokerage equal to 0.25%. The tariff is the same; the denominator changed. Neither percentage describes the ETF’s annual management fee.
The chart is not a recommendation to delay investing until a particular amount accumulates. It isolates one cost so you can evaluate your own contribution pattern. A platform can advertise zero brokerage while fund costs, spreads or service charges still exist. Macquarie’s ETF FAQ explicitly separates issuer fees, fund transaction costs and investor brokerage. Fund costs versus broker charges ↗.
Read a factsheet without turning it into a recommendation.
Use a real document to practise finding information, then repeat the same checks for the product you are considering. Our example is Vanguard’s Australian Shares Index ETF, code VAS, in a factsheet dated 30 September 2026. It is a fixed source example, not a selection or a statement that the current document will always show these figures.
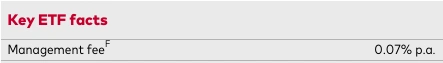
That document identifies the S&P/ASX 300 Index as the benchmark and lists a management fee of 0.07% a year. At a constant A$10,000, that headline rate corresponds to A$7 for one year. It is a management-fee illustration only: the factsheet sends readers to the PDS for the fuller cost breakdown. Vanguard factsheet and qualifications ↗.
Do not stop at the attractive number. The benchmark tells you what the fund is trying to follow; the cost note tells you where the summary stops. Those two fields answer different questions. A fund could have a low headline fee and still be the wrong exposure for the purpose you have in mind.
Start with orientation.
Identify the product, objective, benchmark, date and summary facts.
Check the terms.
Read the strategy, risks and complete fee explanation, including qualifications.
Read the intended audience.
Understand the described target market and distribution conditions.
A Target Market Determination, or TMD, is not personal advice and is not a replacement for the Product Disclosure Statement. Macquarie’s explanation makes that distinction explicit. Treat it as another document in the reading pack, not an individual approval to buy. What a TMD does and does not do ↗.
Before comparing documents, record their dates and check the issuer’s current document library for replacements or supplementary information. A saved factsheet makes a useful historical reference, but an old fee or strategy summary should not silently become a current claim. Issuer document library ↗.
Buying an ETF: the decisions before the button.
Consider Alex, a fictional investor who has already chosen an investment objective and is examining an ETF. This is a process illustration, not a recommendation that Alex—or you—should buy it. The fund’s identity and account details come first; a ticker entered into a search field is only the beginning.
- Identify the exact product. Match the code, full name, exchange and issuer. Save the relevant documents and the reason the exposure fits the task being considered.
- Read the account requirements. Confirm available cash, fees, minimum order rules and how the platform will record the holding. Do not borrow another broker’s requirements.
- Inspect the quote. Check bid, ask, available quantities and whether the relevant market is open. Separate an indicative reference from an executable price.
- Choose an order condition. Understand the price condition, quantity and expiry before submission. Review the estimated cash requirement and brokerage together.
- Check what actually happened. An order acknowledgement is not the same as an executed trade. Retain the confirmation and reconcile units, price and charges.
CommSec explains that a limit buy sets the highest price the buyer is willing to pay, while an at-market order accepts available market prices. A limit is a price boundary, not a promise the order will execute. The precise order types and conditions offered by your own platform need checking. Order-price conditions explained ↗.
Suppose Alex chooses a limit of A$50 for 100 units. If sellers only offer units above A$50, an immediate fill is not assured. If only some units trade, Alex should inspect the remaining order rather than assuming the full intended quantity is already owned. Writing down the intended maximum cash amount makes it easier to spot a quantity or price-entry mistake before committing.
ASX describes ordinary exchange ETF settlement as T+2: two business days after the transaction. Check the trade confirmation for the actual settlement date; a weekend or holiday is not another business day. That timetable concerns completion of the trade, not a guarantee about a platform’s separate cash-withdrawal process. ASX settlement explanation ↗.
Keep the distribution and tax records separate.
Income paid by a fund is generally called a distribution. Macquarie’s ETF FAQ describes distributions as variable and not guaranteed. The amount and timing depend on the fund rather than a promise inherent in the ETF label. Read that product’s distribution policy and announcements instead of carrying over another fund’s calendar. Issuer distribution guidance ↗.
If reinvestment is available, check the election process and deadline. Reinvesting changes what happens to the payment; it does not mean the associated records cease to matter. Keep any election acknowledgement and allocation statement, and reconcile the units actually added rather than assuming every cash amount buys an exact whole number of units.
Betashares says its investors receive an individualised tax statement after the financial year showing income components. This is why adding up bank credits is not a complete substitute for obtaining the issuer’s tax documents. The exact reporting process depends on the fund and your circumstances. Issuer tax-statement guidance ↗.
For an Australian tax return, follow the applicable ATO ETF guidance ↗ and the actual annual statement, with professional help where needed. This guide does not calculate a tax liability or assume a reader’s residency.
Many holdings can still mean concentrated exposure.
ASX’s introductory material distinguishes market movements, currency exposure, tracking differences and risks associated with the investment structure. An exchange listing does not remove those risks. Ask which exposures dominate and what would hurt them together. ASX ETF benefits and risks ↗.
- Sector A: 55%
- Sector B: 25%
- Other sectors: 20%
Even 100 individual holdings would not turn this example into an equally weighted mix of sectors.
Imagine that the fictional portfolio above contains 100 securities. More than half its value is still exposed to Sector A. Counting names answers “How many holdings?”; the weights answer “Where does most of my money depend on outcomes?” Neither number can replace the other.
The same reasoning applies across funds. Two ETFs can contain different numbers of securities yet share several large exposures. Adding a second ticker does not automatically add a new kind of diversification. Before expanding a portfolio, compare the underlying regions, sectors and large positions, including investments you already hold elsewhere.
Use a simple stress question: “If the main exposure fell sharply, where else in my finances would I feel the same event?” This is a way to identify concentration, not a prediction or a formula for an allocation. If you cannot explain the exposure without referring to last year’s return, you may need more information before comparing funds.
A one-page note before your first order.
You do not need to memorise every term in this article. Keep a short evidence note that captures the product, purpose and assumptions. It should be readable later when a price change, new fee or unfamiliar statement makes you question what you bought.
Your ETF reading checklist
- Identity: full name, code, issuer and document dates.
- Purpose: the exposure you intend to obtain and the benchmark or objective.
- Structure: how exposure is achieved and where that is explained.
- Costs: fund-cost disclosure, expected order brokerage, spread and account charges.
- Risks: the largest exposures and the conditions you do not yet understand.
- Records: holding arrangement, registry contact and expected statements.
Leave unanswered questions visible. A blank next to “How are fees charged?” is more informative than copying a generic “low cost” label. If two products seem equivalent, compare the missing fields before picking the one with the most appealing recent chart.
Finally, separate an explanation from an instruction. Understanding the mechanism is necessary, but it does not establish whether a particular investment fits your finances, timeframe or capacity for loss. The useful outcome of this guide is a better set of questions and a traceable document pack, not an automatic purchase decision.
Questions the ETF label does not settle.
Are ETFs and index funds the same thing?
No. “Index” describes an investment approach; “exchange-traded” describes how the fund is accessed and traded. There are active ETFs, while an index strategy can also be offered through an unlisted fund. Read the product structure and strategy separately. Our LIC vs ETF comparison explains company shares, fund units and price-to-backing differences.
Does zero brokerage mean no cost?
No. It describes one potential charge. Inspect the fund’s fee disclosures, the trading spread and any platform conditions. Our hypothetical calculator deliberately keeps these categories separate.
Does a higher unit price mean a more expensive fund?
A single unit’s quoted price is not the annual fee rate. In a hypothetical comparison, ten units at A$100 and one hundred units at A$10 both represent A$1,000 before transaction costs. Neither unit price tells you the quality or value of the underlying investments.
Can I see my ETF units in a CHESS statement?
That depends on the holding arrangement. Use the broker’s terms and your records, then follow our HIN, SRN and custody document guide. A provider screen alone does not establish the registration structure.
Official guidance, with the examples kept separate.
Sources checked 23 October 2026. The Vanguard example is dated 30 September 2026; the document date is not today’s market data. Original diagrams and hypothetical figures explain the mechanics, and no private account or trade was used to prepare this guide.
- ASIC MoneySmart: ETF structure and types ↗
- ASX: ETF and ETP introduction ↗
- ASX: trading, NAV and settlement ↗
- ASX: market-maker arrangements ↗
- CommSec: limit and at-market order conditions ↗
- Betashares: fund-fee collection ↗
- Macquarie: ETF costs and distributions ↗
- Betashares: registry and statement enquiries ↗
- Vanguard: official VAS factsheet ↗
- Macquarie: the role of a TMD ↗
Recheck this guide when exchange settlement arrangements, official guidance or the example fund’s disclosures change. Tax details, foreign-domiciled products, complex strategies and product suitability require their own applicable documents. This guide does not replace them.